What Happens if I Ignore Subrogation
Ignoring subrogation doesn't stop it, it just lets the insurer's claim against you grow while your options shrink.
Free to compare
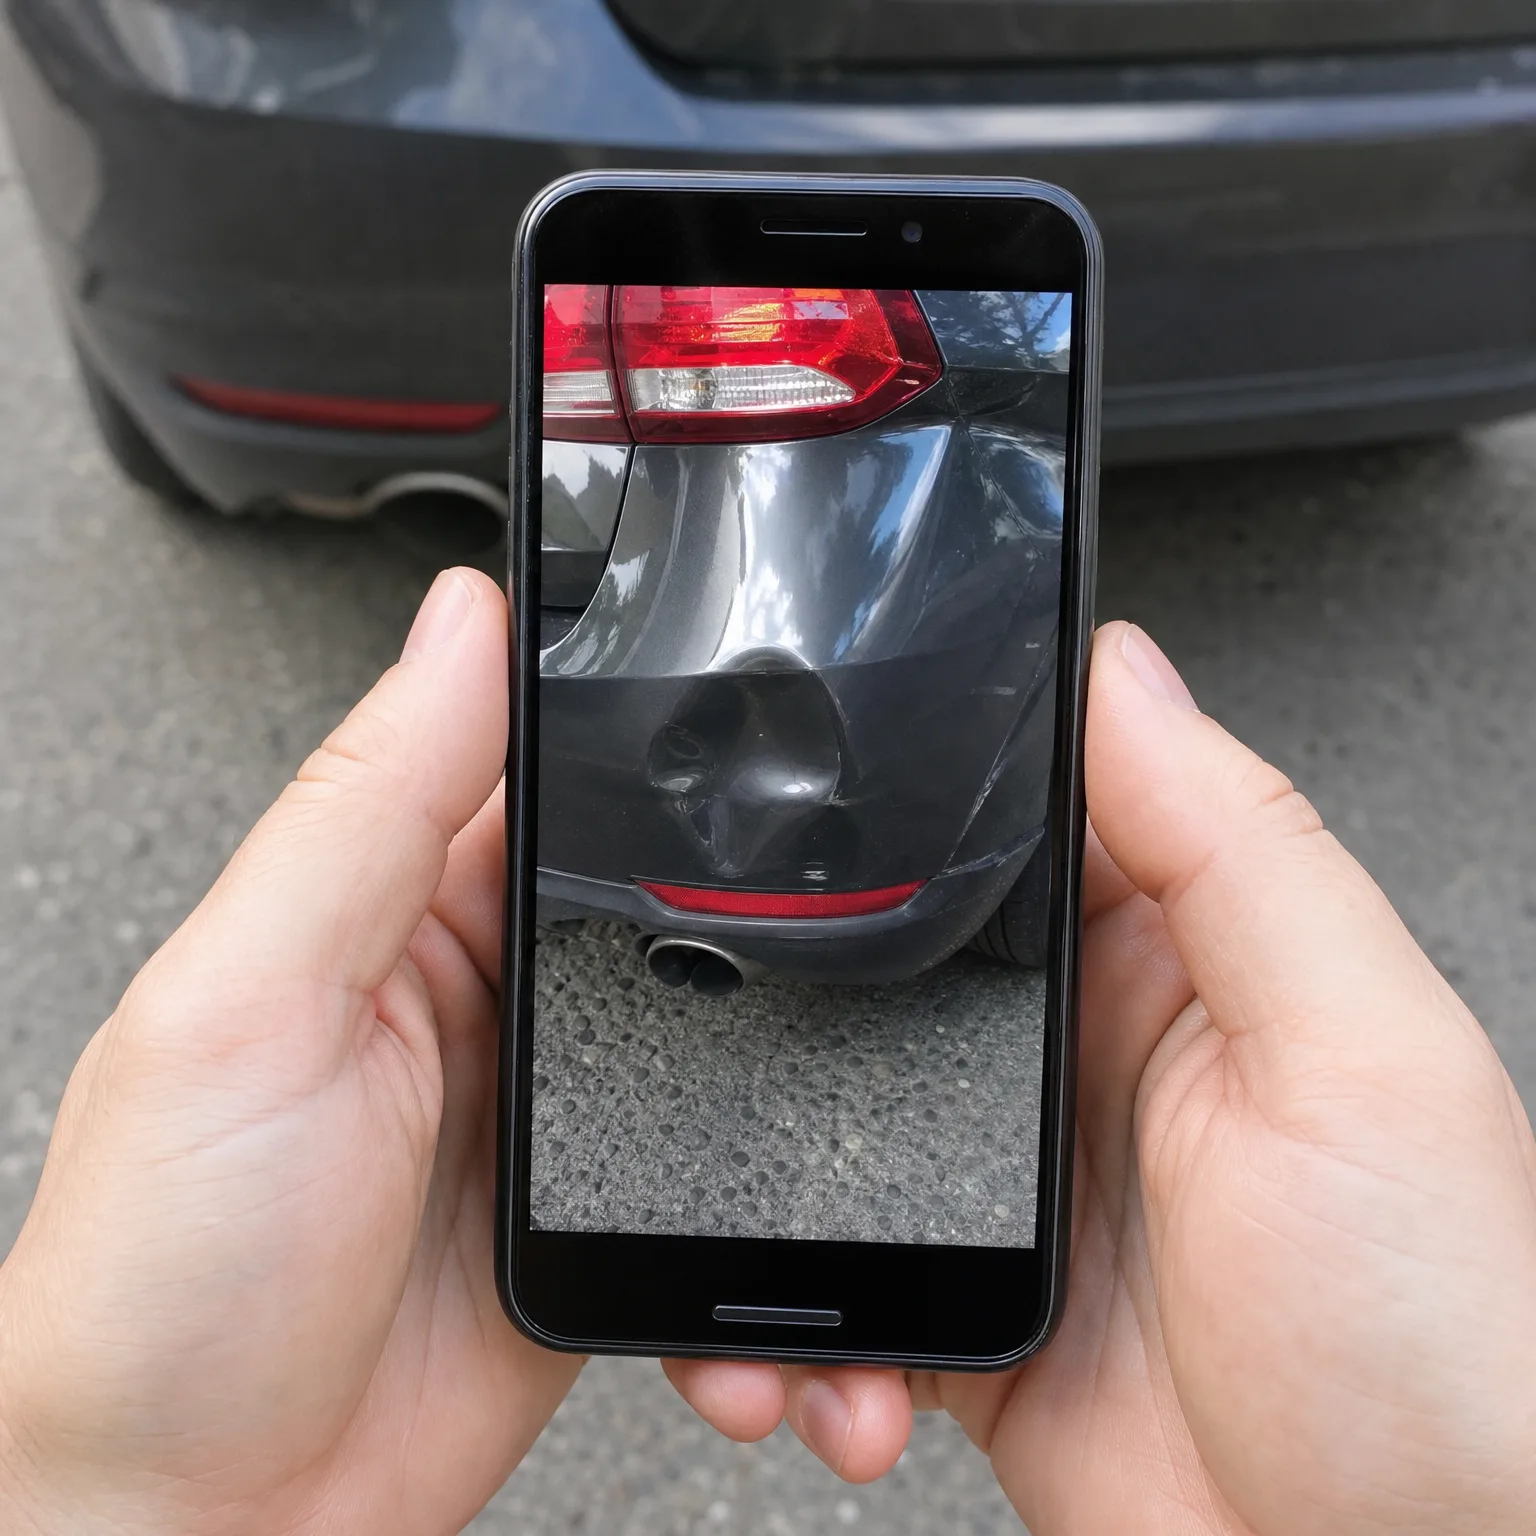
What ignoring subrogation actually costs you
- The debt doesn't expire An insurer's subrogation claim stays open whether you answer or not. Respond to any letters or calls, even just to say you got them, so it's on record.
- Your own insurer gets pulled in If the other driver's insurer can't reach you, they may go through your insurance company instead. That can affect your premium and your relationship with your own insurer.
- It can turn into a lawsuit If the amount is significant, the insurer can sue you to recover it. Don't wait for a court date to deal with this, respond while it's still a conversation.
- It can hurt credit or license An unpaid judgment can become a collections account, and in some states unpaid accident debt can affect your driving privileges. Check your state's rules so you know what's actually at stake.
- Your SR-22 stays complicated If you're already carrying an SR-22, an open subrogation claim adds another item insurers see when pricing your policy. Clearing it up helps you look less risky going forward.
Can subrogation make my insurance rates go up even more?
Yes, it can. If the claim shows you were at fault, or partly at fault, the insurer handling subrogation will likely report that outcome, and your own insurer may use it when your policy renews. This is separate from whatever rate increase you're already dealing with from the original accident or the SR-22 requirement.
How much it affects your rate depends on your insurer's rules and your state's regulations, so ask your agent directly what a subrogation finding would do to your premium. In some cases, if you dispute the claim successfully or if fault is shared, the impact is smaller than you'd expect. The worst outcome usually isn't the subrogation itself, it's letting it go unanswered until it turns into a judgment, which tends to hurt more than the original claim would have.
Once you know what's actually on the line, compare quotes and get back to a policy that fits where you are now.
Answering the subrogation claim versus letting it sit
If you do
You respond, explain your side if you have one, and either pay, negotiate, or dispute the amount. The claim gets resolved on a timeline you have some say in. Your insurer stays out of a bigger mess, and you avoid court costs or added debt stacking on top of what you already owe.
If you don't
The insurer keeps trying to collect, then refers it to collections or files suit. You lose the chance to negotiate the amount. A judgment can follow, which may show up on your credit and make your SR-22 insurance and future coverage harder and pricier to get.
Why subrogation doesn't just fade away
Subrogation exists because insurance companies pay claims fast, often before fault is fully sorted out, and then recover the money from whoever was actually responsible. That recovery right doesn't expire just because you don't answer the phone. The insurer has already paid out real money, and they have both the legal standing and the financial motivation to keep pursuing it.
What changes when you ignore it is not whether they pursue you, but how. Insurers generally try the easy path first, letters, calls, maybe a settlement offer. If that doesn't work, they move to formal collections or legal action, which costs them more but also gives them more leverage, like a judgment that accrues and attaches to your assets or wages depending on your state.
This is also where your SR-22 status matters more than it might for other drivers. You're already flagged as higher risk, and an unresolved subrogation claim sitting on your record is one more thing underwriters see when pricing a policy. Clearing the debt, or at least showing it's being actively handled, can matter more for you than for someone without that history.
The cases where it plays out differently usually involve disputed fault. If you have a real argument that you weren't responsible, or only partly responsible, raising that early changes the whole process. Insurers are more willing to negotiate before they've spent money on collections or legal fees than after.
A subrogation claim doesn't disappear if you wait, it just gets more expensive to fix.